Management Packages: The Final BOFiP Has Been Published
TAX UPDATE NEWSLETTER
OCTOBER 2026
Management packages:
—the final BOFiP has been published
What's New in the Final Version of the Administrative Comments, Taking into Account the 2026 Budget Act: 12 Key Points to Remember.
REFERENCE
BOI-RSA-ES-20-60
Published on October 15, 2026
The Essentials
Our selection of 12 key points
Beneficiaries
Employees and executives of the issuing company, its parent company, or its subsidiaries.
➜ A manager who left before the sale is still considered part of the calculation: what matters is the source of the gain. The tax authorities may also choose to disregard amended clauses.
§ 190
Concept of a counterparty
A combination of factors: performance-based clawback, non-transferability clauses, leaver’s awards…
➜ The portfolio must include a performance-based mechanism (ratchet, sweet equity); the other metrics are merely supplementary.
§ 190
Pending: the treatment of pari passu shares held alongside ratchet shares.
Length of Detention
2 years minimum prison term to qualify for the program
➜ Takeover bids, mergers, spin-offs, divisions, and consolidations: ownership of the securities tendered in exchange is retained, provided that the shareholder waives any cash adjustments and fractional shares.
§ 132
Please note: Based on the current text of the law and the BOFiP, this continuity does not apply to contribution transactions.
Tax Cap
Capital gains are taxed up to an amount equal to the acquisition price multiplied by three times the financial return (the ratio of equity at the time of exit to the time of entry); amounts exceeding this limit are treated as wages and salaries.
➜ Valuation method of choice (equity value, NAV, DGFiP guidelines); shareholder debt repaid prior to the sale is added to the exit value; capitalized interest on debt instruments not added back at the time of acquisition.
§ 370 · § 390
Pending: Many practical questions remain regarding the measurement of financial performance.
Dividends Before the Sale
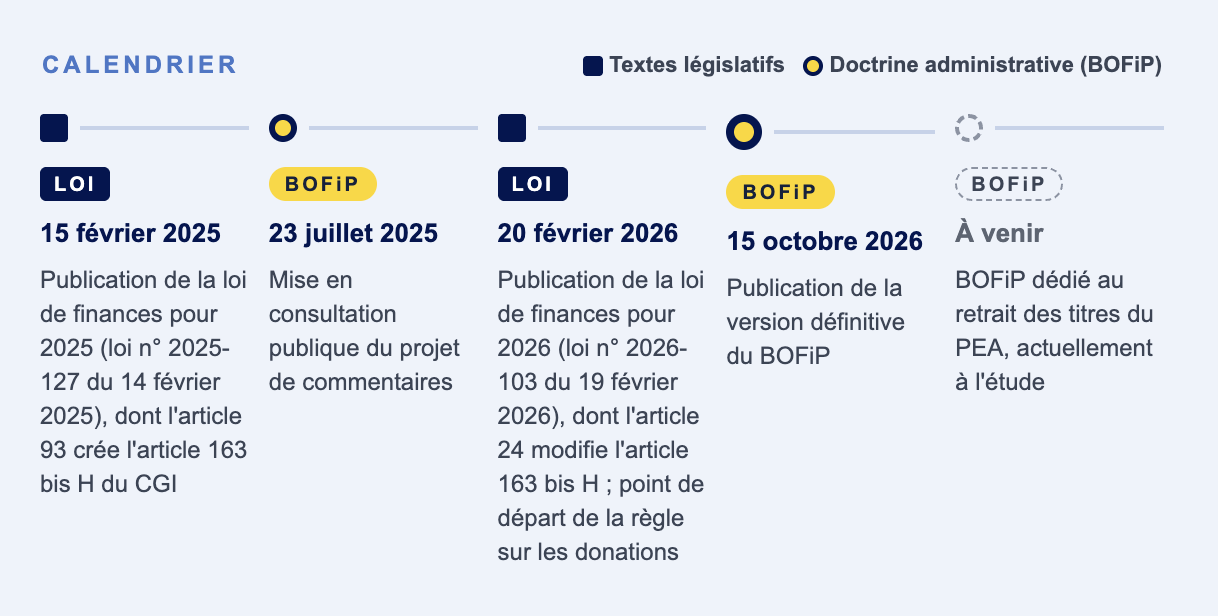
Amendment made by the 2026 Finance Act and incorporated into the BOFiP.
➜ The tax cap is adjusted if the manager received distributions before selling his or her securities.
Art. 24 of the 2026 Act
Tax Deferral
In the event of a securities exchange, particularly a rollover, the excess portion taxed as wages may be carried forward. This provision applies to transactions conducted on or after February 15, 2025.
Note: The BOFiP does not address the inconsistency in the text, which requires that the company employing the manager be owned by the new LBO vehicle prior to reinvestment. This requirement is completely at odds with standard practice, where such transactions generally occur simultaneously.
Art. 24 of the 2026 Act
Cost
The aggregate value of all eligible securities of a single company sold by the beneficiary, regardless of their nature or the rights they confer.
➜ New: “blending” is permitted between the reference company and a Manco that holds only its own securities, limited to securities eligible under the scheme.
§ 280 · § 285
Net taxable income
The BOFiP confirms that the tax base is net income.
➜ The gain is reduced by the fees and taxes paid by the seller in connection with the sale.
§ 150
Price Supplements
An earn-out is taxed in the year it is paid, added to the initial purchase price, and subject to the same cap, calculated as of the date of sale.
➜ Permitted: an earn-out indexed to the performance of a subsidiary of the sold company or its group.
§ 610 · § 630
International Situations
The classification under domestic law does not preclude the classification under the applicable tax treaty.
➜ Non-resident working partly in France: in principle, this constitutes a capital gain under the terms of the treaties, unless otherwise specified.
§ 240
Donations
Donations of securities from management packages made on or after February 20, 2026 (2026 Finance Act).
➜ Net gain taxed in the donor's name in the year of the gift: a transfer without consideration no longer eliminates the unrealized gain.
§ 640
Pending : the possibility of maintaining a tax-clearing effect on the portion of the gain classified as capital gains.
PEA
Withdrawals may be made from “neutral” accounts (LF 2026): without closing the account or the bank deducting social security contributions.
➜ Terms not specified (cost basis after withdrawal), and no information on double taxation regarding social security contributions for transfers occurring from February 2025 through February 2026. A dedicated BOFiP is reportedly under consideration.
Further details expected
Zoom
How is the profit broken down?
INITIAL VALUE
Opening equity balance, excluding capitalized interest on debt instruments
OUTPUT VALUE
+ debts owed to shareholders or related companies that were repaid prior to the sale § 390
CEILING
Purchase price × 3 × financial performance (equity outflow / inflow), adjusted for distributions received
Accepted Valuation Methods § 370:
Market Value (Equity Value)
Net Asset Value
DGFiP Evaluation Guide
Net gain on disposal, after expenses and taxes § 150
Capital Gains Tax Treatment
up to the maximum limit
Compensation and Salaries
for the excess, which can be carried forward in the event of a rollover
Illustrative proportions.
Earn-out: Taxable in the year it is paid, it is added to the initial purchase price and counts toward the same tax cap, which is fixed as of the date of sale (§ 610 · § 630).
OUR COMMITMENT
Alongside employee representative bodies, the Scotto firm has initiated numerous proposals to improve the system, which it is advancing—together with ALESI—in its discussions with the Tax Legislation Directorate and the government, and intends to continue this dialogue in the coming months.
Your contacts
The partners in the tax practice are available to discuss this with you
PRIVATE EQUITY (MANAGEMENT)
Beyond Taxation
For any general questions about your management package (negotiation, documentation, governance), our Private Equity partners are here to assist you.
Stay informed
Check back regularly for our latest news
Find our analyses and newsletters on our website and on LinkedIn.
About Scotto
A pioneer in management packages in France, Scotto has been advising founders, executives, managers, and family-owned groups for 30 years, operating completely independently of financial investors. Beyond negotiating and structuring compensation packages, the firm assists its clients with all long-term financing transactions (LBOs, mergers and acquisitions, capital raises, and restructurings), as well as with their tax matters and the transfer of their wealth, both in France and internationally.
Tax Update Newsletter · October 2026
