Management Packages: The BOFiP “PEA” Has Been Published
TAX UPDATE NEWSLETTER
NOVEMBER 2026
Management packages:
—the BOFiP on “PEA” has been published
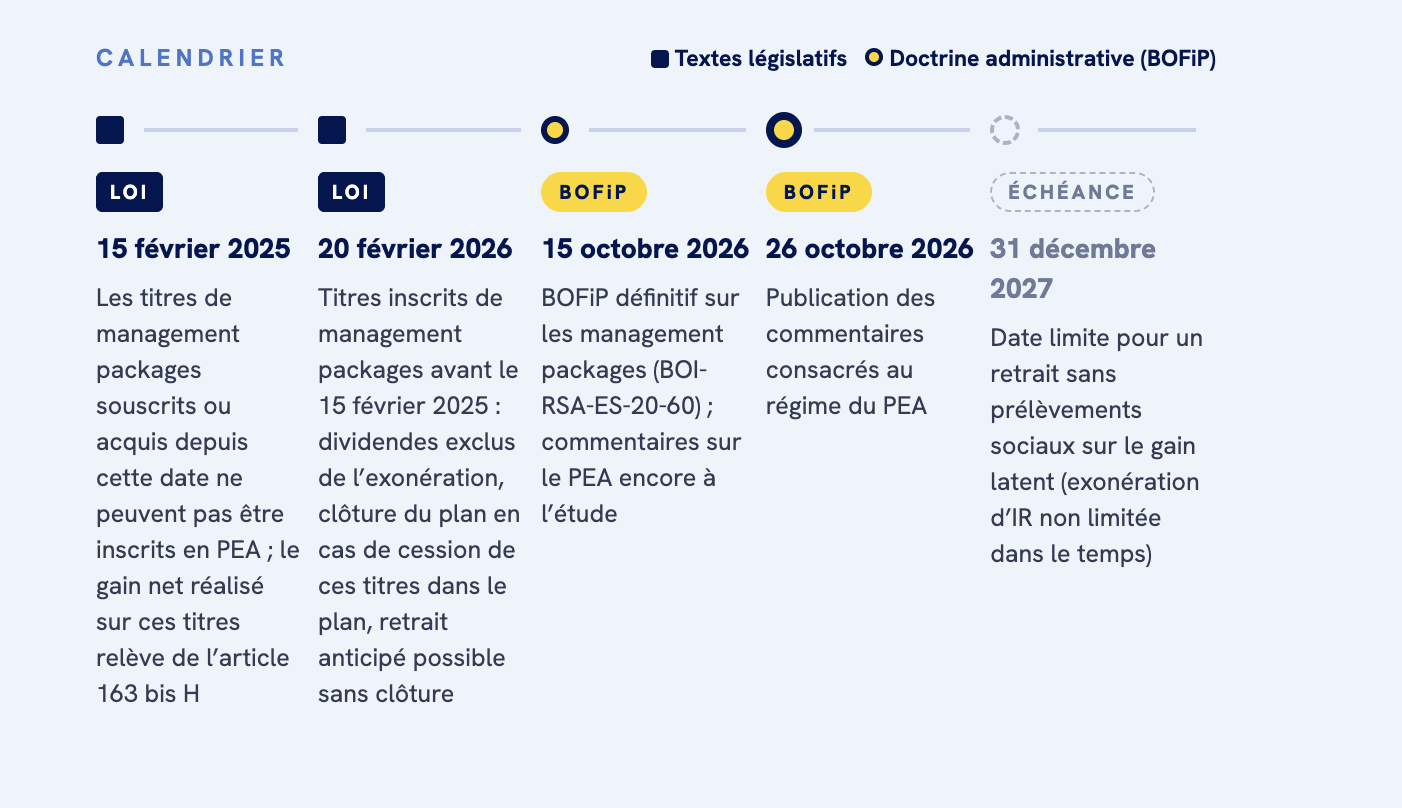
Following the publication of the final BOFiP on management packages, the tax authorities updated their comments on the PEA regime on October 26, 2026. These comments incorporate changes to the tax and social security treatment of management package securities held in the plan, as set forth in the 2025 (Art. 93) and 2026 (Art. 24) Finance Acts:
Practical Insights and Uncertainties
PUBLICATION
October 26, 2026
Comments on the PEA Program
The Essentials
Our selection of 8 key points
No Tax Exemption for Income Earned in a PEA
Exclusion from the PEA tax exemption for securities held in management packages.
➜ Confirmation: Proceeds from management package securities held in a PEA will, effective February 20, 2026, be taxed under the general tax regime for investment income.
BOI-RPPM-RCM-40-50-30 § 5
Our interpretation: The BOFiP thus clarifies the interpretation that could already be drawn from the texts.
Ineligibility of New Securities
Securities in management packages subscribed to or acquired on or after February 15, 2025, cannot be held in a PEA.
The net gain realized on these securities since that date is subject to the special provisions of Article 163 bis H of the CGI.
BOI-RPPM-RCM-40-50-20-20 § 540
Withdrawal of securities without closing the PEA account
Securities held in management packages may be withdrawn from the PEA prior to their sale, regardless of how long the PEA has been open.
Note: The gain on withdrawal is not subject to income tax or social security contributions (for withdrawals made on or before December 31, 2027), regardless of whether the plan has been in effect for more or less than five years.
BOI-RPPM-RCM-40-50-40 § 350 · § 360
Withdrawal Procedures
The withdrawal request submitted to the plan administrator must be accompanied by a sworn statement.
➜ The certificate specifies that the securities fall under Article 163 bis H and states their market value as of the date of withdrawal.
BOI-RPPM-RCM-40-50-60 § 170
Pending: the determination of market value as of the date of withdrawal, particularly for unlisted securities.
Unrealized Gain on the PEA
In the event of a subsequent sale of securities withdrawn from the PEA, the acquisition price used to determine the capital gain is equal to the purchase or subscription price of the securities in the plan, not their value on the date of withdrawal.
Uncertainty: The BOFiP refers to the 2026 Finance Act without addressing practical questions, particularly regarding the treatment of prior capital gains. Indeed, when securities from management packages were received in a PEA as part of an exchange (contribution, merger, etc.) carried out before February 15, 2025, the capital gain from the exchange was realized before Article 163 bis H of the CGI took effect.
BOI-RPPM-PVBMI-20-10-20-20 § 205
Contributions to the plan
The portion of the payments corresponding to the securities withdrawn is deducted from the payments used to calculate the gain on subsequent withdrawals and the closing gain of the PEA.
Uncertainty: Does this portion also count toward the cash contribution limit for the PEA (i.e., €150,000 for the PEA / €225,000 for the PEA-PME)?
Are new contributions still possible after a withdrawal made before five years have elapsed? The BOFiP does not specify this.
BOI-RPPM-RCM-40-50-40 § 370
Otherwise, the PEA would remain cluttered with securities that are no longer included in it, and closing it to open a new one would result in the loss of the plan’s tax seniority.
Sale of Assets in a PEA
As of February 20, 2026, a capital gain realized on securities held in management packages within a PEA (without a prior withdrawal) results in the closure of the plan. This gain is taxed separately—in accordance with the tax rules governing management packages—from the gain resulting from the closure of the plan.
⚠️ Important note: If you plan to sell, be sure to withdraw the securities before the sale (certificate, valuation, manager’s processing times).
BOI-RPPM-RCM-40-50-50 § 10
Double Social Taxation
If securities held in a management package within a PEA are sold before February 20, 2026, and if the gain has been reported by the taxpayer prior to any withdrawal from the PEA, that gain is taxed through an assessment, and the bank then applies social security contributions at the time of a future withdrawal or account closure. This situation therefore results in double social security taxation.
➜ Note: The BOFiP sets forth specific procedures for eliminating double social security taxation. This is achieved either by offsetting social security contributions or by filing a claim. See our overview below for details and a numerical example from the BOFiP.
BOI-RPPM-RCM-40-50-30 § 6 · § 7
Pending: The BOFiP does not address the risk of double social security taxation in the event of a withdrawal from a PEA prior to the taxpayer’s reporting of the gain and prior to assessment by the tax authorities.
Zoom
How is double social security taxation eliminated?
The finding: situations prior to February 20, 2026. Gains on management packages realized in the PEA were taxed through an assessment; the social security contributions (PS) subsequently withheld by the bank at the time of withdrawal or account closure constitute double taxation. For plans lasting more than five years, the BOFiP provides for a two-step adjustment, upon request.
Step 1 · Payroll Allocation
It is deducted from the withdrawal or closing proceeds: any excess PS is refunded. The undeducted balance is carried over to the next withdrawal.
Step 2 · Capital Gains Allocation
Any remaining PS is refunded, up to the amount of PS paid through the tax assessment. This limit is reduced as refunds are issued.
The BOFiP Example (1/2) · PEA opened in 2019, sale as part of the plan in July 2025, net gain of €280,000 taxed under Article 163 bis H via the tax assessment roll
€230,000
Capital gains portion
50,000 €
Salary portion
The two "reservoirs" of restitution
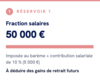
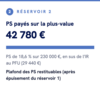
The BOFiP Example (2/2) · For each transaction, the bank deducts 18.6% as PS; upon request, reserves ① and then ② are tapped
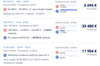
Key points: The bank must apply social security contributions as usual, without any adjustment to eliminate double taxation; a refund of social security contributions requires filing a claim no later than December 31 of the second year following the deduction, along with the tax assessment notices and the plan’s settlement statement (§ 280 · § 290).
Glossary. PS: social security contributions (CSG, CRDS, solidarity levy). Tax assessment: tax paid based on a tax assessment notice. Wage portion: the portion of income exceeding the threshold, taxed as wages. Example: BOI-RPPM-RCM-40-50-30 § 7.
In summary
What the BOFiP Addresses, What Remains Unresolved
Key Contributions / Confirmations from the BOFiP
Exclusion of securities from management packages from the PEA plan (capital gains and dividends)
Withdrawal without closing the account, exempt from income tax and social security contributions
Restatement of Payments for Future Earnings
Elimination of Double Social Taxation in the Event of a Withdrawal from a PEA After the Taxpayer Has Reported the Gain
Key Contributions / Confirmations from the BOFiP
Amount of prior capital gains realized in a PEA
Impact of the Withdrawal on the Limit and Payments
Double Social Security Taxation in the Event of a Withdrawal from a PEA Before the Taxpayer Reports the Gain
Assessment of Market Value as of the Date of Withdrawal
Good Habits
Five Things to Keep in Mind for Owners
Identify the securities registered before February 15, 2025, that fall under Article 163 bis H.
Withdraw securities before making any sales: Selling securities in a PEA results in the account's closure.
Attach the sworn statement and provide documentation of the market value as of the date of withdrawal.
Plan ahead for December 31, 2027, to ensure a withdrawal free of social security contributions.
Keep tax assessment notices and settlement statements on file for claims
Since every situation is unique, a case-by-case analysis is recommended.
OUR COMMITMENT
Alongside employee representative bodies, the Scotto firm has initiated numerous proposals to improve the system, which it is advancing—together with ALESI—in its discussions with the Tax Legislation Directorate and the government, and intends to continue this dialogue in the coming months.
Your contacts
The partners in the tax practice are available to discuss this with you
PRIVATE EQUITY (MANAGEMENT)
Beyond Taxation
For any general questions about your management package (negotiation, documentation, governance), our Private Equity partners are here to assist you.
Stay informed
Check back regularly for our latest news
Find our analyses and newsletters on our website and on LinkedIn.
About Scotto
A pioneer in management packages in France, Scotto has been advising founders, executives, managers, and family-owned groups for 30 years, operating completely independently of financial investors. Beyond negotiating and structuring compensation packages, the firm assists its clients with all long-term financing transactions (LBOs, mergers and acquisitions, capital raises, and restructurings), as well as with their tax matters and the transfer of their wealth, both in France and internationally.
Tax Update Newsletter · November 2026


